

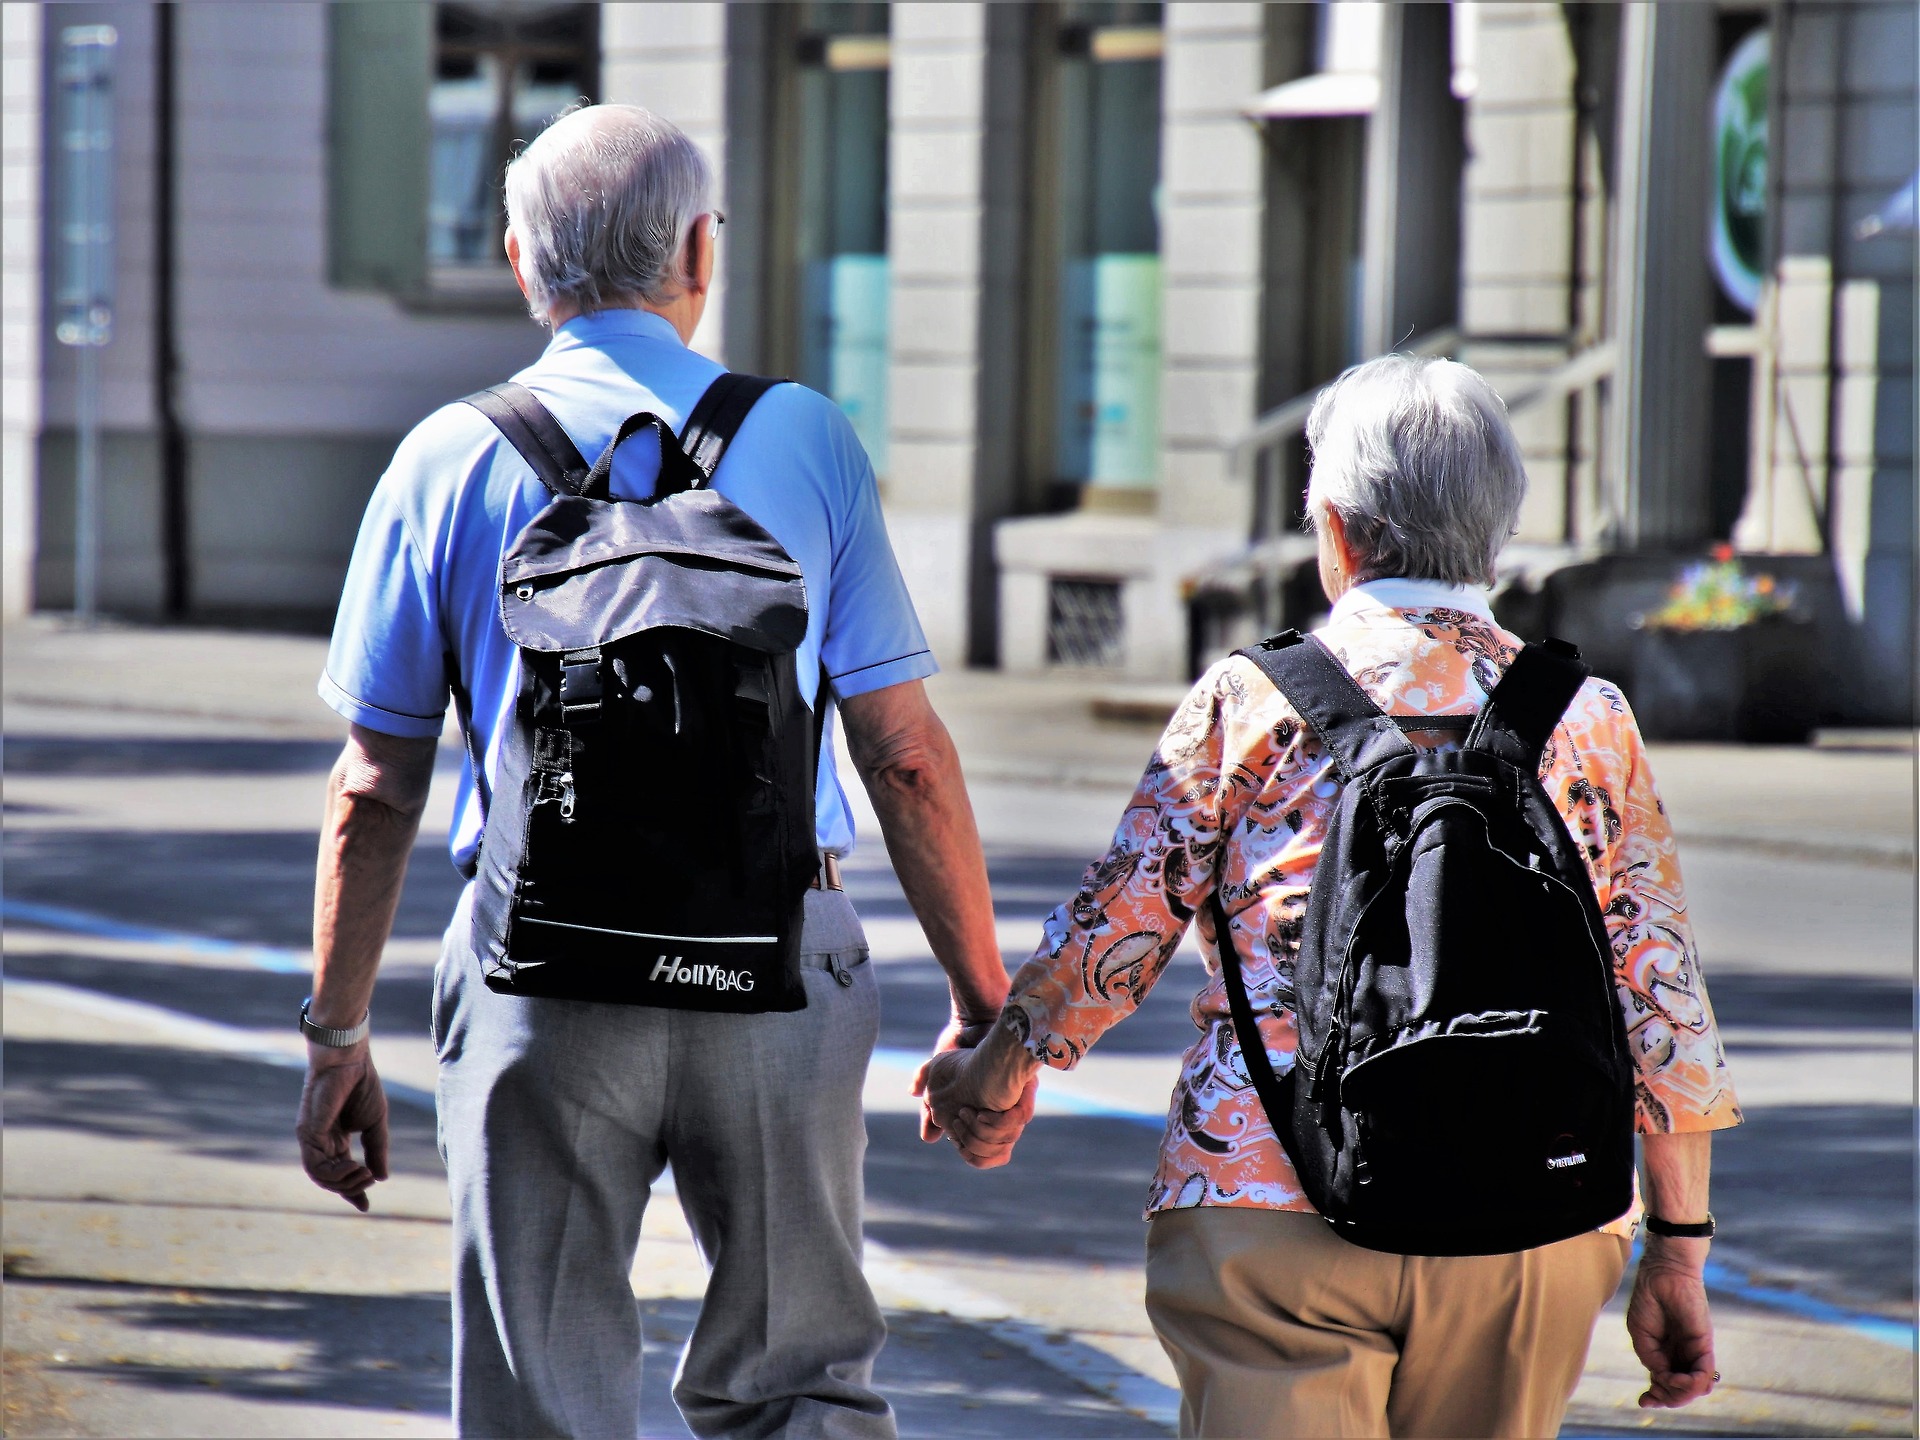
Longevity is civilisation’s trophy and its invoice. Every added year of life expectancy is a gift to the person living it and a line item in the pension system supporting it — and the systems, as reporting by the BBC keeps noting, were priced for a shorter gift. The adjustment now under way is reshaping retirement ages, savings behaviour and the meaning of a career’s final third.
What makes the moment interesting is that the adjustment is no longer purely defensive. Longer lives have produced a generation of healthy sixty- and seventy-year-olds whose work, spending and volunteering are economic forces in themselves. The pension question is merging with a larger one: what is a hundred-year life for?
The Arithmetic Nobody Escapes
Pay-as-you-go state pensions rest on a ratio: contributors per pensioner. That ratio has been falling for decades as fertility dropped and longevity rose, and no honest projection makes it recover on its own. The levers are few and known — later retirement, higher contributions, lower relative benefits, or more immigration and productivity to widen the base.
Every government pulls some combination, usually late and under protest. The countries that moved earliest and most gradually — linking retirement age to life expectancy automatically, for instance — have bought stability at the price of a hard political argument held once, rather than repeatedly.
The New Shape of a Working Life
Careers are stretching and bending in response. Phased retirement, portfolio work and late-life retraining are moving from eccentricity to expectation; employers facing skills shortages have discovered the experienced worker they once ushered out. Age discrimination law is acquiring, at last, a business case behind it.
The health dimension decides much. Longer lives are not automatically healthier ones, and the fairness argument burns hottest where it is ignored: a system that asks everyone to work longer lands very differently on the scaffolder than on the professor. The serious reforms build in the carve-outs; the lazy ones breed the backlash that kills them.
Saving in the Auto-Enrolment Age
Private provision has been quietly revolutionised by inertia used for good: workers are enrolled by default into pension saving, and most stay. The pots accumulating are the largest experiment in mass long-term saving ever run, and their adequacy — contributions set in a less inflationary age — is the next argument in the queue.
Financial guidance is rushing to fill the advice gap: dashboards that show a saver their whole retirement position, decumulation products that turn pots back into income, and a slow cultural shift in which the pension statement is read as attentively as the payslip. Longevity demands literacy, and the literacy is arriving with the longevity itself.
Annuity markets, moribund in the low-rate era, have revived with higher yields — insurers report record sales of guaranteed lifetime income. The product our grandparents bought without thinking is being rediscovered by a generation that has learned what market risk feels like in retirement.
The Opportunity in the Long Life
It is worth ending the arithmetic with the asset side. Societies with more healthy, experienced older citizens have more mentors, carers, volunteers and consumers with time. Businesses are learning to sell to the longevity economy; policymakers are learning, slowly, to design for it rather than merely fund it.
The pension system will be renegotiated for the rest of our lives — it is the price of the renegotiation of life itself. Done well, the outcome is not a longer sentence of work but a longer, more various life, financed with open eyes.
We asked for longer lives and got them. The pension debate is simply what gratitude looks like when it meets arithmetic. The systems that thrive will be those that treat a hundred-year life not as a liability to be managed, but as the new normal to be designed for.
Read more in our Finance section, and follow the day’s coverage on our homepage.
